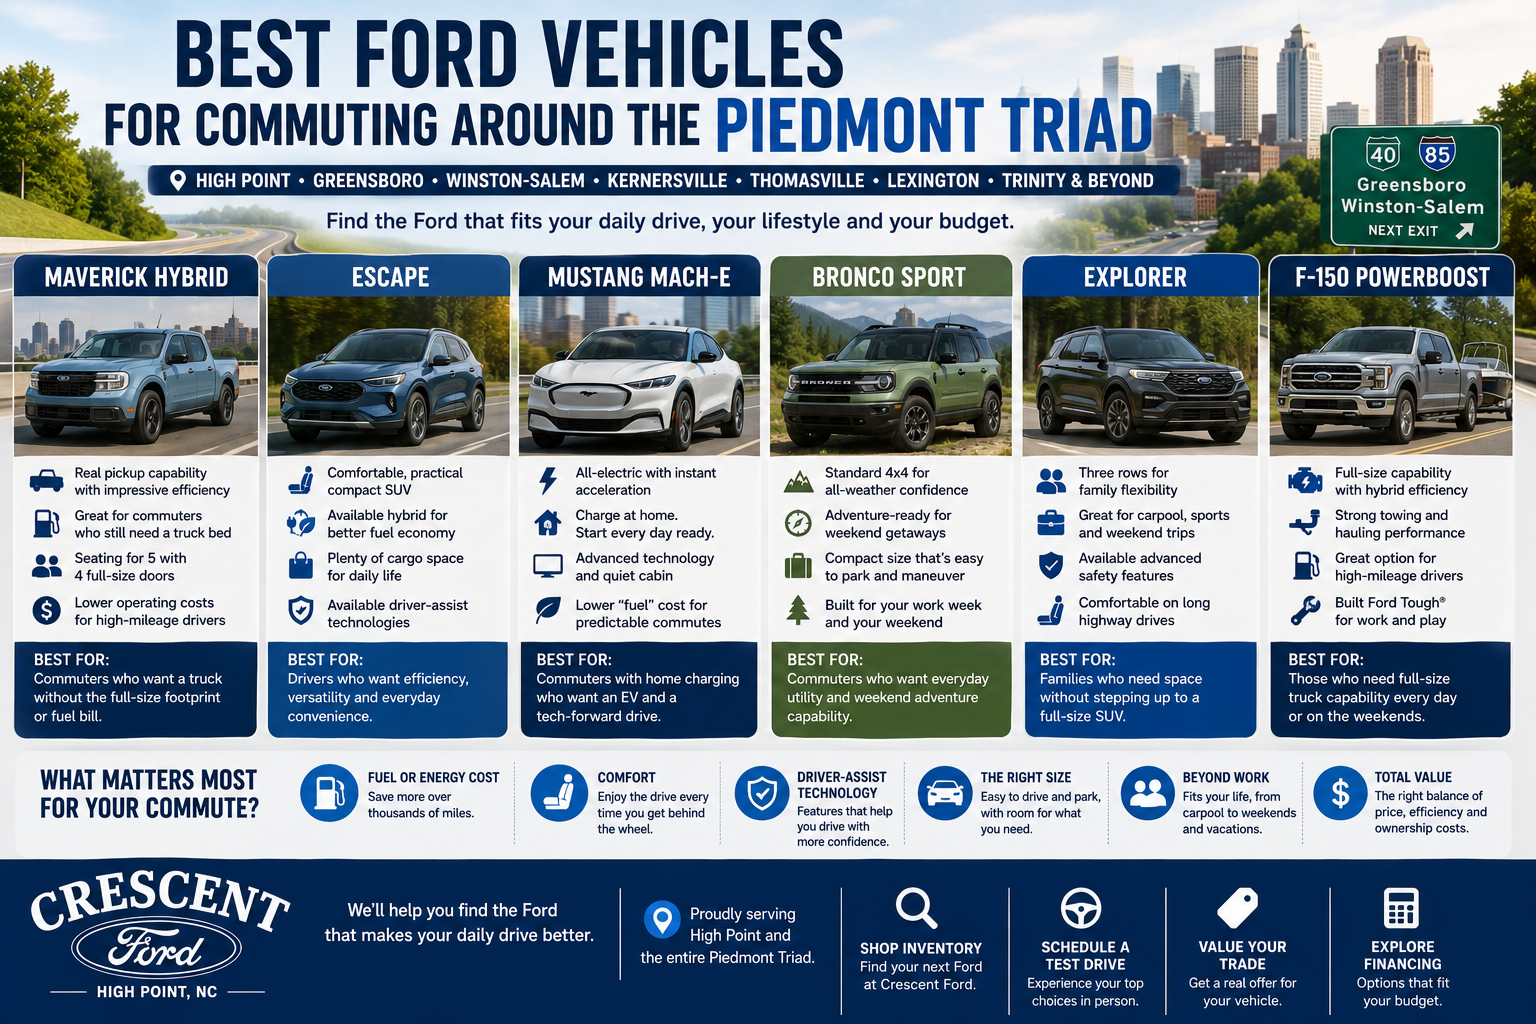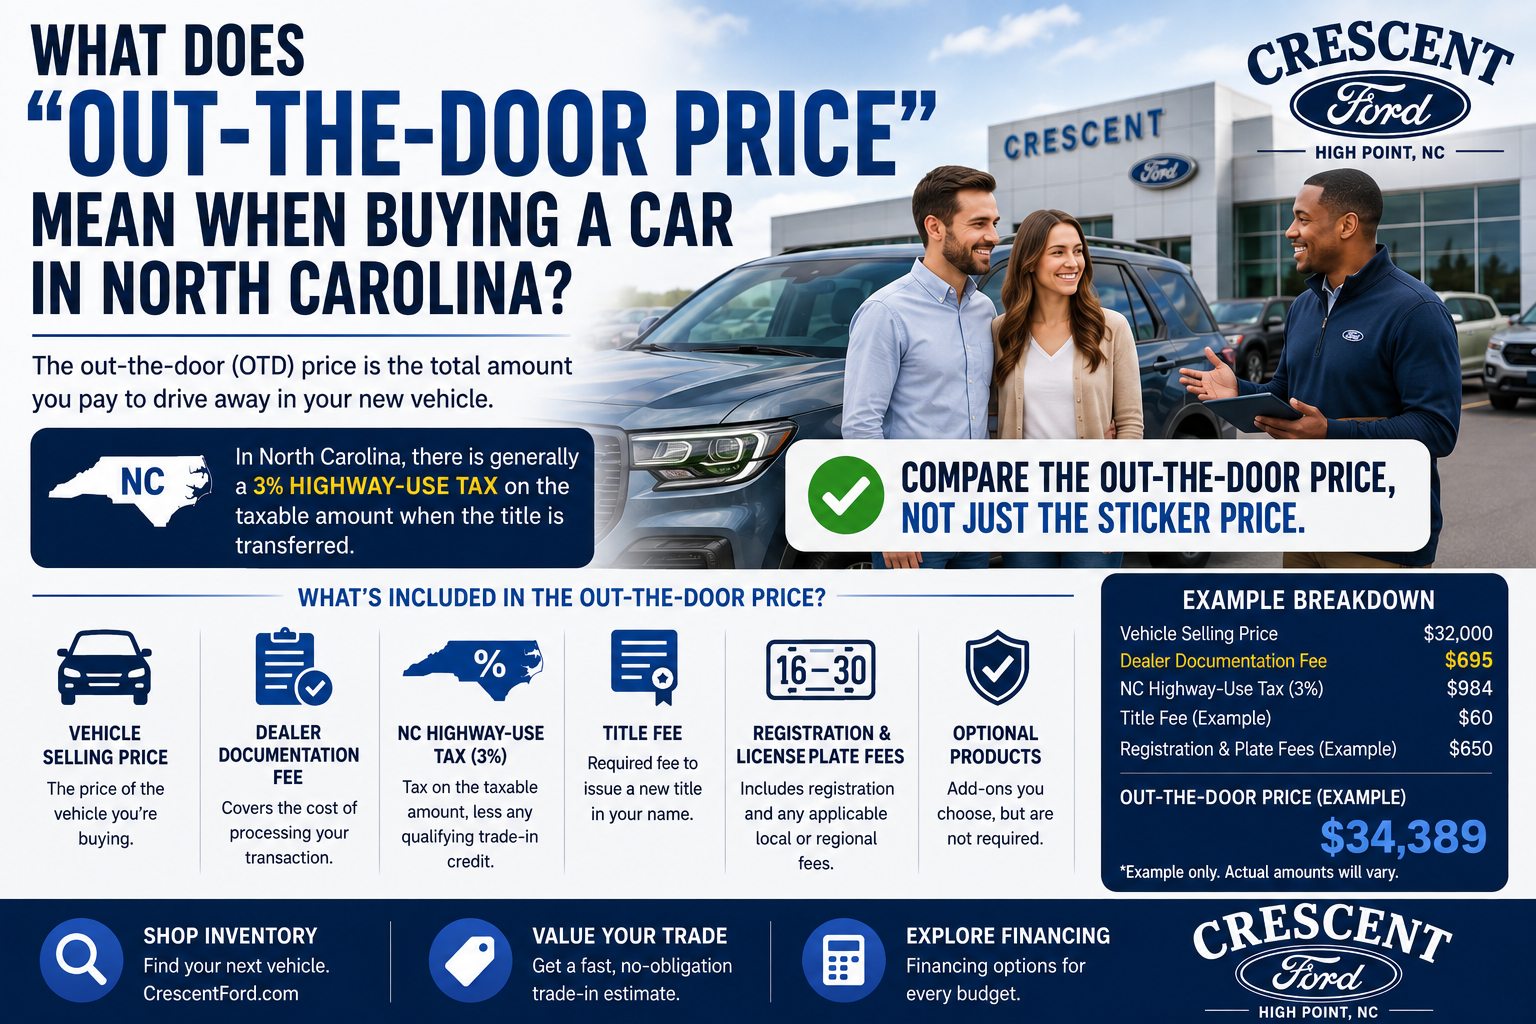

How Much Should You Put Down on a Car? You've found a car you like. You've figured out roughly what you want your monthly payment to be. Then comes another question: How much money should you actually put down? You've probably heard plenty of rules. "Always put 20% down." "Ten percent is enough." "Never put money down on a car." "Put down as much as possible." The problem? None of those rules works for every buyer. There are good reasons to make a larger down payment. There are also situations where putting thousands of dollars down may not be the best use of your cash. And if you have a trade-in with equity, you may already have a down payment without writing a check at all. So instead of giving you an arbitrary percentage, let's look at what a down payment actually does — and how to decide what makes sense for your car purchase. Explore Auto Financing Options How Much Should You Put Down on a Car? The Quick Answer There isn't a universal amount that every buyer should put down. You'll often see 10% to 20% used as a general guideline, with some financial experts recommending even more. But that's a guideline — not a requirement. The better goal is to put down enough to: Keep the amount you're financing manageable Get a monthly payment that fits comfortably in your budget Reduce the amount of interest you'll pay Establish some equity in the vehicle Meet any lender requirements Avoid draining savings you may need for emergencies For one shopper, that could be $5,000. For another, it might be $1,000. Someone with substantial trade equity may not need to bring any additional cash at all. And some buyers may qualify to purchase a vehicle with little or no money down. The important question isn't: "What's the normal down payment?" It's: "What does putting more or less down do to this particular deal?" What Is a Down Payment on a Car? A down payment is money or equity applied toward the vehicle purchase upfront rather than financed as part of your auto loan. Suppose your amount to be financed before a down payment is $35,000. If you put $5,000 down, you'd reduce that amount to approximately $30,000, assuming everything else remains the same. That's important because you're now borrowing less money. And when you borrow less money, several other things can change. What Does a Bigger Down Payment Actually Do? A larger down payment can provide several benefits. 1. It reduces the amount you finance This is the most obvious one. If you put $5,000 down, that's $5,000 you don't have to borrow. 2. It can lower your monthly payment Borrowing less generally means a lower monthly payment when the APR and loan term stay the same. 3. It can reduce the interest you pay Interest is charged on the money you borrow. Reduce the amount borrowed, and you can reduce the total interest expense over the life of the loan. 4. It can improve your equity position Vehicles depreciate. Starting with more money down can help create a cushion between what the vehicle is worth and what you owe. 5. It may help with financing approval Depending on your credit profile, vehicle and lender, a lender may require a certain amount of money down. A down payment can reduce the lender's risk because you're financing a smaller portion of the transaction. But that doesn't mean: More down is always better. We'll get to that. How Does a Down Payment Affect Your Car Payment? Let's use a simple hypothetical example. Suppose you're financing a vehicle at $35,000 before any down payment. We'll use an example 7% APR for 60 months purely to demonstrate the math. Your actual APR will depend on your credit, lender, vehicle, loan term and available financing programs. Down Payment Approx. Amount Financed Approx. Monthly Payment $0 $35,000 $693 $2,500 $32,500 $644 $5,000 $30,000 $594 $7,500 $27,500 $545 $10,000 $25,000 $495 Hypothetical example only. Excludes taxes, fees, optional products and other transaction-specific amounts. That's a useful way to think about a down payment. In this example, every additional $2,500 down reduces the payment by roughly $50 per month. But here's where we want you to think beyond the payment. Would you rather have: $5,000 in your savings account and a payment around $693? or $0 of that $5,000 in savings and a payment around $594? There isn't enough information to answer that question yet. That's exactly the point. Your emergency savings, income stability, other debt and overall financial situation matter too. Is 10% a Good Down Payment on a Car? Ten percent can be a reasonable starting point for many shoppers, but don't treat it as a magic number. On a $30,000 vehicle, 10% would be: $3,000. On a $50,000 vehicle: $5,000. On a $70,000 truck: $7,000. The percentage may be the same, but those are very different amounts of cash. Before deciding that you "need" to put 10% down, look at what that money actually accomplishes. Ask: How much does it lower my payment? How much interest does it save? Does the lender require it? How much cash will I have left afterward? Do I already have trade equity? Would some of that cash be better used to pay down higher-interest debt? A percentage is a starting point—not a financial strategy. Should You Put 20% Down on a Car? Putting 20% down can put you in a strong equity position and substantially reduce the amount you're financing. But again, don't blindly follow the rule. Imagine you're buying a $45,000 vehicle. Twenty percent is: $9,000. If you have $40,000 sitting in savings and no high-interest debt, putting $9,000 down may be perfectly comfortable. If you have $10,000 total in savings? Putting $9,000 into a depreciating asset and leaving yourself with $1,000 for emergencies is a completely different decision. That's why we prefer: "How much can I comfortably put down?" over: "What percentage am I supposed to put down?" Can You Buy a Car With No Money Down? Potentially, yes. Some buyers may qualify for financing with $0 cash down, depending on factors such as: Credit Income Vehicle Amount financed Loan-to-value Lender requirements Trade equity Current financing programs But qualifying for $0 down and deciding that $0 down is your best financial choice are two different things. If you finance more of the purchase, you'll generally have: A larger loan A higher monthly payment More interest expense Less initial equity That doesn't make a zero-down purchase inherently bad. Keeping your cash might be valuable for other reasons. It simply means you should understand the tradeoff. Talk With Our Finance Team When Does $0 Down Make Sense? There are situations where keeping your cash can be reasonable. You have a very favorable interest rate If you're financing at a particularly low promotional APR, you may decide that keeping cash available is more valuable than using it to reduce a low-cost loan. Manufacturer financing programs change regularly, so this decision should be based on the actual offer available when you're shopping. You need to preserve an emergency fund Buying a car shouldn't leave you unable to handle an unexpected home repair, medical bill or other emergency. You already have substantial trade equity This is a big one. You might say: "I'm not putting any money down." But if your trade has $7,000 of positive equity and you apply that toward the transaction, you effectively have $7,000 reducing what you need to finance. No additional cash may be necessary. The payment already fits comfortably If your payment, loan term and total financing cost are reasonable without cash down, you may decide that keeping your savings is more important. When Should You Consider Putting More Money Down? There are also situations where we'd strongly consider a larger down payment. Your monthly payment is too high If the payment doesn't fit comfortably into your budget, a larger down payment can reduce it. But there's an important warning here: Don't use a huge down payment to make an unaffordable vehicle look affordable. If you have to empty your savings just to make the monthly payment work, you may simply be shopping for too much vehicle. Your lender requires it Depending on the transaction and credit profile, the lender may require money down for approval. You want to reduce total interest If you're borrowing at a higher APR, reducing the principal can become increasingly valuable. You want a stronger equity position A larger down payment can help reduce the chance that you'll owe significantly more than the vehicle is worth, particularly early in the loan. You're financing for a longer term If you're considering a longer loan, starting with more equity deserves additional consideration because you'll be paying down principal more slowly. Can Your Trade-In Be Your Down Payment? Absolutely. This is one of the most important things for shoppers to understand. Suppose your current vehicle is worth: $20,000 and your loan payoff is: $13,000. You have approximately: $7,000 in positive equity. If you trade the vehicle and apply that equity toward your next purchase, that $7,000 reduces the amount that otherwise needs to be financed. You may not need to bring additional cash. Find Out What Your Vehicle Is Worth Related Reading What Is My Car Worth in High Point, NC? How Trade-In Appraisals Actually Work Can You Trade In a Car You Still Owe Money On? What If You Have Negative Equity? Now we have the opposite situation. Suppose your vehicle is worth: $20,000 but you still owe: $24,000. You're approximately $4,000 upside down, or $4,000 in negative equity. That doesn't necessarily prevent you from trading. Depending on lender approval and the overall transaction, some or all of that negative equity may potentially be included in the new loan. But this is a situation where bringing money down can become particularly valuable. If you bring $4,000, for example, you could potentially offset that negative-equity amount rather than carrying it forward into your next loan. The specifics depend on the transaction and lender approval, but the principle is simple: Money down can help prevent old debt from becoming new debt. That's something worth discussing with the finance team before choosing your next vehicle. Should You Put Your Entire Trade Value Down? Not necessarily. If you own your trade outright, you have choices. Suppose your vehicle is worth $15,000 and you owe nothing. You could apply all $15,000 toward your next vehicle. But depending on the transaction, you may also want to discuss whether there are other options for how your equity is handled. The important thing is knowing what the vehicle is worth first. Your trade is part of your financial picture. Don't treat it as an afterthought. Should You Use Your Savings for a Car Down Payment? This is where we'd be cautious. Having $10,000 in a savings account doesn't automatically mean you should put $10,000 down. Before taking money from savings, consider: Your emergency fund Upcoming expenses Other debts The APR on those debts Job/income stability The auto-loan APR How much the additional down payment actually saves you Here's an extreme example: Suppose you have $10,000 in cash. You also have $5,000 in high-interest credit-card debt. Putting the entire $10,000 down on a relatively low-interest auto loan while continuing to carry expensive credit-card debt may not be the most efficient use of your money. This is where the "put as much down as possible" advice falls apart. Your car loan doesn't exist in isolation from the rest of your finances. Does a Bigger Down Payment Lower Your Interest Rate? Not automatically. A larger down payment reduces the amount you're borrowing, but your APR is determined by factors that can include: Credit history Credit score Loan term Vehicle Lender Amount financed Loan-to-value Current programs A larger down payment may help make a transaction more attractive to a lender or help meet lending requirements, but don't assume putting another $2,000 down automatically lowers your APR. Ask. Compare the actual financing scenarios. Does a Down Payment Help You Get Approved? It can. From a lender's perspective, financing $25,000 on a particular vehicle can present a different risk than financing $35,000 on that same vehicle. A down payment can reduce the loan-to-value ratio and the amount the lender is being asked to finance. For some borrowers, that may help create a financeable structure. But there's no universal amount that guarantees approval. Credit history, income, debt obligations, vehicle and lender guidelines still matter. What If You Have Bad Credit? If your credit is challenged, you may encounter lenders that require money down as part of the approval. In that situation, the question changes from: "How much do I want to put down?" to: "What financing structures are actually available to me?" That doesn't mean you should automatically agree to the first option presented. Look at: APR Amount financed Down payment Monthly payment Loan term Total of payments You want an affordable vehicle and an understandable loan. How Do I Get a Car Loan With Bad Credit? Is It Better to Put Money Down or Choose a Shorter Loan? This is a great question because both can reduce financing costs. Let's say you have enough income to handle a higher monthly payment. You might compare: Option A: Larger down payment + 72-month loan with Option B: Smaller down payment + 60-month loan Which is better? You can't tell from those descriptions alone. You need the actual: APR Amount financed Monthly payment Total interest Total of payments A shorter term generally means a higher monthly payment but can reduce the amount of interest paid. A larger down payment reduces the principal from the beginning. Sometimes the best answer is a combination of both. Explore Your Auto Financing Options Don't Choose Your Down Payment Based Only on the Monthly Payment This deserves its own section. Suppose you tell a salesperson: "I need to be at $500 per month." There are several ways the math could potentially get there. You could: Put more money down Choose a less expensive vehicle Extend the loan term Qualify for a lower APR Apply trade equity Use some combination of those factors Those aren't financially equivalent. Putting $8,000 down to reach $500 per month isn't the same thing as putting $2,000 down and reaching $500 because you qualified for a lower rate. And neither is the same as reaching $500 by extending the loan substantially. That's why we'd encourage shoppers to look at: Vehicle price + trade value + down payment + APR + term + payment + total financed rather than focusing on the payment alone. New vs. Used: Should Your Down Payment Be Different? You may see traditional rules recommending a larger percentage down on a new vehicle than a used vehicle. There's some logic behind that. A new vehicle begins its depreciation cycle when you purchase it, so putting more down can help establish an equity cushion. A used vehicle has already experienced some depreciation. But once again, we'd rather compare the actual transaction. A nearly new used vehicle with a high APR may benefit from a larger down payment. A brand-new vehicle with an attractive manufacturer APR may make keeping more cash appealing. There isn't a universal percentage that accounts for those differences. Related Reading Should You Buy New or Used in 2026? A Real-World Cost Comparison What About Taxes and Fees? This is another reason your down-payment calculation shouldn't begin and end with the vehicle's advertised price. The amount you're actually financing can include more than the vehicle price. Depending on the transaction, you'll also need to account for applicable: Taxes Registration Title fees Dealer documentation fees Optional products you choose to purchase Negative equity, if applicable That's why understanding the out-the-door price is useful before deciding how much cash to put down. Related Reading What Is the Out-the-Door Price of a Car? A Better Way to Decide How Much to Put Down Instead of starting with a percentage, try this process. Step 1: Determine what you can comfortably afford Figure out a comfortable vehicle budget before worrying about how to structure the loan. Step 2: Find out what your trade is worth You may already have thousands of dollars in equity available. Step 3: Find out your payoff Trade value minus payoff tells you whether you have positive or negative equity. Step 4: Look at your financing options Find out the actual APR and terms available to you. Step 5: Run several down-payment scenarios Ask to see the difference between: $0 down $2,500 down $5,000 down or whatever amounts are realistic for you. Step 6: Look at both payment AND total cost Don't stop when you see a monthly payment you like. Step 7: Protect your cash reserves Ask yourself what you'd have left after making the down payment. Step 8: Choose the balance that makes sense The goal isn't to put the most money down. It's to create a vehicle purchase that works comfortably within your finances. How Much Should You Put Down on a $30,000 Car? Let's make this practical. On a $30,000 vehicle: 5% = $1,500 10% = $3,000 15% = $4,500 20% = $6,000 That doesn't mean $6,000 is automatically the "correct" answer. If $3,000 creates a comfortable payment and allows you to maintain healthy savings, that may be more appropriate. If you have $6,000 in trade equity already, you may not need additional cash. If the lender requires $4,000 for the transaction, then your situation is different again. How Much Should You Put Down on a $40,000 Car? On $40,000: 5% = $2,000 10% = $4,000 15% = $6,000 20% = $8,000 Again, run the loan both ways. Seeing how much an additional $2,000 changes the payment and total interest makes the decision much easier than following an arbitrary rule. How Much Should You Put Down on a $50,000 Car? On $50,000: 5% = $2,500 10% = $5,000 15% = $7,500 20% = $10,000 This is where percentages can start representing substantial amounts of cash. Twenty percent sounds simple until it means moving $10,000 out of your savings account. Make sure the financial benefit justifies what you're giving up in liquidity. How Much Should You Put Down on a $60,000 Truck or SUV? On $60,000: 5% = $3,000 10% = $6,000 15% = $9,000 20% = $12,000 For higher-priced trucks and SUVs, trade equity can become especially important. If your current truck is worth $30,000 and you owe $20,000, that $10,000 in equity may do much of the work without requiring you to bring another large amount of cash. Value Your Trade Before You Shop Should You Put Money Down on a 0% APR Car Loan? This is one of the situations where the answer becomes especially interesting. If you qualify for a genuine 0% APR offer, you're not paying interest on the financed amount under the terms of that loan. That removes one of the major financial reasons for making a larger down payment: reducing interest expense. You may still choose to put money down to: Lower the payment Reduce the amount financed Create additional equity Meet program or lender requirements But if no down payment is required, you may prefer to keep more cash available. There is no universal answer. Also remember that manufacturer 0% APR programs are generally available only on certain vehicles, terms and for qualified buyers when offered. They may sometimes be an alternative to other incentives. Compare the complete offers before choosing. Should You Put Money Down on a Lease? A lease is different from financing a purchase. Generally, we'd be cautious about making a large capitalized cost reduction simply to lower a lease payment. Why? Because you're putting a substantial amount of cash upfront into a vehicle you don't own. Lease structures, requirements and protections can vary, so if you're considering leasing, ask the finance team to show you: Amount due at signing Any required fees Payment with minimal upfront cash Payment with additional cash down Then compare them before deciding. Don't put several thousand dollars down simply because the lower advertised monthly payment looks attractive. What Is the Best Down Payment on a Car? The best down payment isn't necessarily 10%. It isn't necessarily 20%. And it definitely isn't: "As much as you possibly can." A good down payment is one that helps create an affordable loan without putting the rest of your finances under unnecessary pressure. Ideally, after the transaction: Your payment fits comfortably. You understand your APR and loan term. You haven't emptied your savings. You have a reasonable equity position. You understand what your trade contributed. You know the total amount you're financing. You're comfortable with the total cost. If that happens with 20% down, great. If it happens with 10%, that's fine too. If you have enough trade equity that you don't need additional cash, that's worth considering. And if you're approved with $0 down, compare that option against putting money down before deciding. There is no prize for putting the most money down. The goal is to structure the purchase intelligently. Calculate Your Down Payment at Crescent Ford in High Point, NC If you're shopping for a new Ford or used vehicle around High Point, Greensboro, Winston-Salem, Kernersville, Thomasville, Lexington, Trinity or the surrounding Piedmont Triad, you don't have to decide on a down payment before you know the rest of the numbers. Start with the vehicle. Find out what your trade is worth. See what financing options are available. Then compare different amounts down. At Crescent Ford, our finance team can show you how changing the down payment affects the amount financed and monthly payment so you can make the decision based on actual numbers rather than an internet rule. Explore Financing at Crescent Ford Value Your Trade Shop New Ford Vehicles Shop Used Cars, Trucks & SUVs Frequently Asked Questions About Car Down Payments How much should I put down on a car? There isn't one required amount for every buyer. While 10% to 20% is commonly discussed as a guideline, the appropriate down payment depends on the vehicle, financing terms, trade equity, lender requirements and your personal finances. Is $2,000 a good down payment on a car? It can be. The more useful question is how $2,000 affects your specific loan. Compare the payment, amount financed and total interest with and without the $2,000 down. Is $5,000 a good down payment on a car? Depending on the vehicle's price, $5,000 can substantially reduce the amount financed. However, make sure making that down payment doesn't leave you without adequate savings for emergencies or other expenses. Is 10% enough for a car down payment? Ten percent is a commonly used guideline, but it isn't a universal requirement. Some buyers may benefit from putting more down, while others may qualify with less or no additional cash down. Is 20% down on a car too much? Not necessarily. A 20% down payment can reduce your loan balance, monthly payment and interest expense while improving your equity position. However, putting 20% down may not make sense if doing so would significantly deplete your savings. Can I buy a car with no money down? Some buyers can qualify for a vehicle loan without a cash down payment. Approval depends on the borrower, lender, vehicle and overall transaction. Keep in mind that financing more generally means a larger loan and higher monthly payment. Does my trade-in count as a down payment? Positive trade equity can be applied toward your next vehicle and reduce the amount that needs to be financed. For example, if your vehicle is worth $20,000 and you owe $13,000, you have approximately $7,000 in positive equity that could potentially be applied to the transaction. Should I put more money down if I have bad credit? A lender may require money down depending on your credit profile and the transaction. Putting more down reduces the amount being financed and may help create a structure a lender will approve, but it doesn't guarantee approval or a particular interest rate. Does putting more money down lower my car payment? Generally, yes. If the interest rate and loan term remain the same, reducing the amount financed with a larger down payment will lower the monthly payment. Does putting more money down lower the interest rate? Not automatically. Your APR depends on factors such as credit history, lender, vehicle, loan term and current financing programs. A larger down payment can reduce how much you borrow even if the APR stays the same. Should I use my entire savings for a car down payment? Generally, you should consider your emergency fund and other financial obligations before using a large portion of your savings for a vehicle. A lower car payment may not be worth leaving yourself without adequate cash reserves. Should I put money down if I have trade equity? You may not need to. Positive equity in your trade can already reduce the amount you need to finance. Compare the transaction using your trade equity before deciding whether adding cash provides enough additional benefit. Can Crescent Ford show me different down-payment options? Yes. Rather than choosing an amount based solely on a percentage, you can compare financing scenarios with different down payments to see how each affects the amount financed and monthly payment. Use the actual financing terms available to you when deciding.
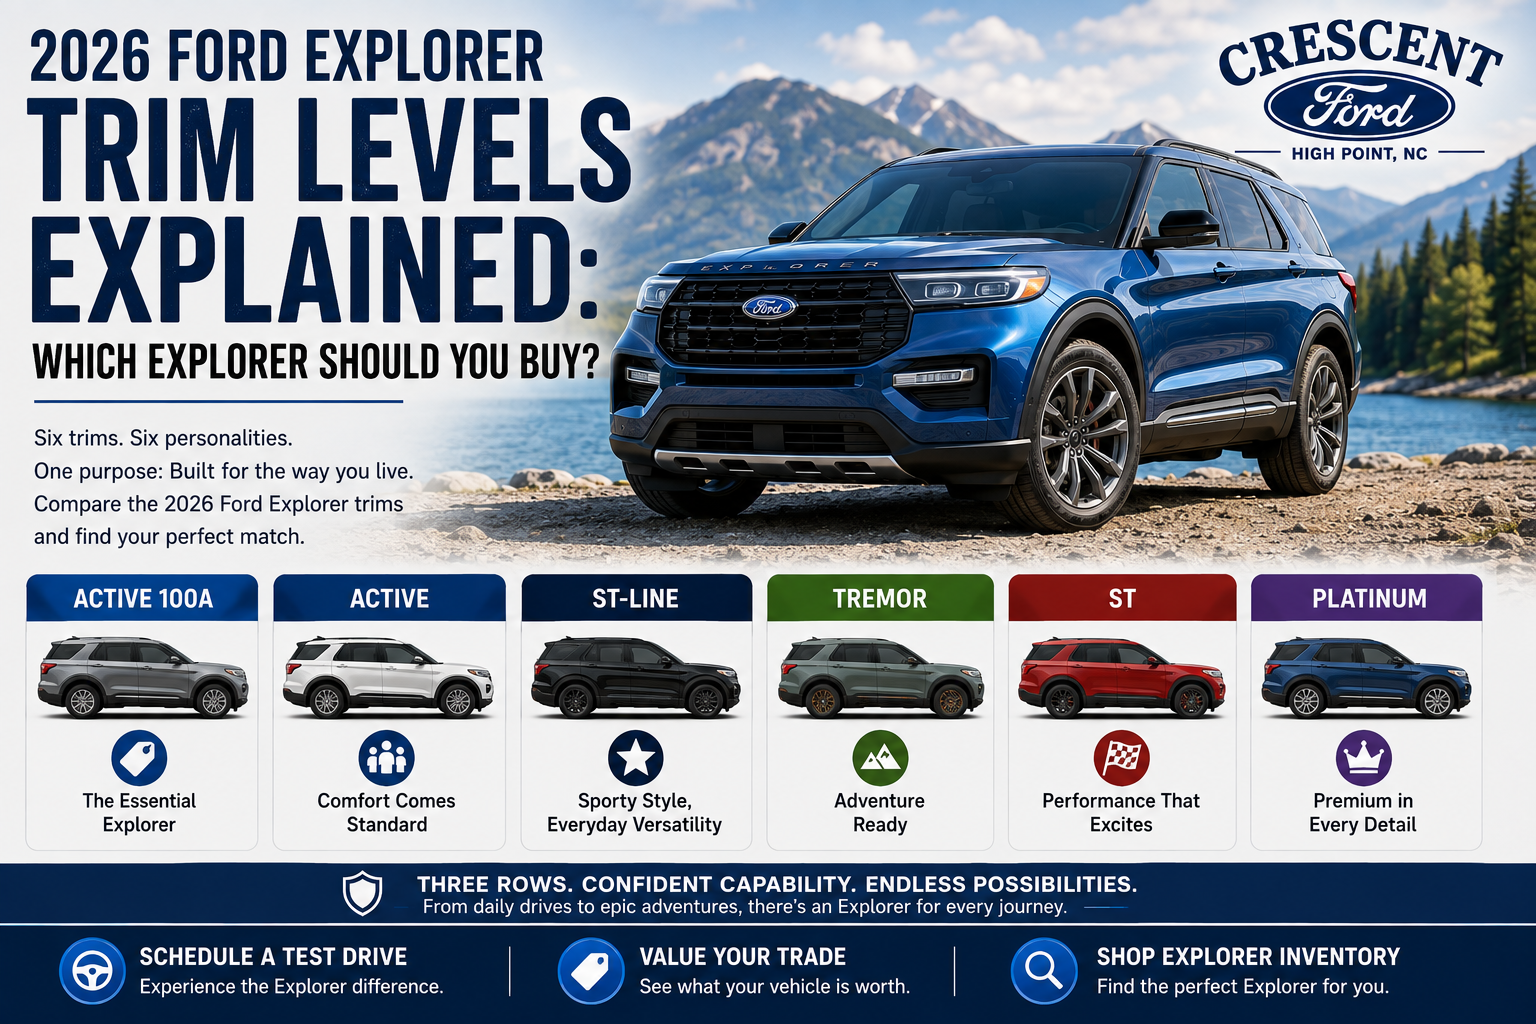
2026 Ford Explorer Trim Levels Explained: Which Should You Buy?
2026 Ford Explorer Trim Levels Explained: Which Explorer Should You Buy? So you've decided the Ford Explorer is probably the right SUV for your family. Great. Now you have another decision to make: Which Explorer should you buy? For 2026, Ford gives Explorer shoppers several distinctly different choices: Explorer Active 100A Explorer Active Explorer ST-Line Explorer Tremor Explorer ST Explorer Platinum And choosing between them isn't simply a matter of working your way up the price ladder. The ST-Line looks sportier without requiring you to move into the high-performance ST. The ST gives you the 3.0L EcoBoost V6 and significantly more performance. The Platinum prioritizes comfort and upscale features. And the new Tremor takes Explorer in a completely different direction with standard 4WD and equipment designed for greater capability away from pavement. In other words: The most expensive Explorer isn't automatically the best Explorer for you. Let's figure out which trim actually fits the way you'll use it. Shop New Ford Explorer SUVs at Crescent Ford 2026 Ford Explorer Trim Levels at a Glance Explorer Personality Engine Drivetrain Best For Active 100A Essential Explorer 2.3L EcoBoost RWD or 4WD Value-focused shoppers Active Comfort-focused 2.3L EcoBoost RWD or 4WD Everyday family use ST-Line Sporty appearance 2.3L EcoBoost RWD or 4WD Style + technology Tremor Adventure/off-road 2.3L EcoBoost; 3.0L available 4WD Outdoor/adventure families ST High performance 3.0L EcoBoost V6 RWD or 4WD Performance-focused shoppers Platinum Luxury-focused 2.3L EcoBoost RWD or 4WD Premium comfort Features and options can vary by equipment group and configuration. Always verify the window sticker and equipment on the individual Explorer you're considering. The quick answer Active 100A: Choose it if your priority is getting into a new Explorer while keeping things simple. Active: Our starting point for many traditional family-SUV shoppers. ST-Line: Choose it if you love the sporty Explorer look but don't need the ST's V6 performance. Tremor: Choose it if 4WD and greater off-pavement capability genuinely fit your lifestyle. ST: Choose it if you want the Explorer that is genuinely fun to drive. Platinum: Choose it if comfort and premium features matter more than maximum performance. Now let's look at why. 2026 Ford Explorer Active 100A: The Essential Explorer The Active 100A is new for 2026 and becomes the entry point into the Explorer lineup. Think of this as the Explorer for someone who says: "I want the space and capability of an Explorer, but I don't need every convenience feature." It uses the same 2.3L EcoBoost four-cylinder engine found in several other Explorer trims and is available with rear-wheel drive or Intelligent 4WD. Where Ford saves money is primarily in equipment. Compared with the regular Active, the 100A simplifies some convenience features. For example, Ford's order guide shows a manual liftgate rather than the Active's power liftgate, simplified front-seat adjustments and other equipment differences. That creates an interesting option for shoppers who care more about: Three-row capability Explorer size Core technology Engine performance Available 4WD Purchase price than having every comfort feature. Who should buy the Explorer Active 100A? Consider it if: You're shopping primarily around budget. You want a new Explorer rather than a smaller SUV. You don't mind a manual liftgate. You don't need premium interior features. You want the 2.3L EcoBoost powertrain. You'd rather spend money on the vehicle size you need than convenience features you don't. Who should move up to Active? If you're already thinking: "Wait — I definitely want the power liftgate." Keep reading. The regular Active may be the better fit. 2026 Ford Explorer Active: The Family Sweet Spot For a lot of Explorer shoppers, Active is where we'd start the comparison. It keeps the 2.3L EcoBoost powertrain but adds comfort and convenience features that can matter during everyday family use. And that's really what Active is about. Not showing off. Not pretending you're headed rock crawling. Not chasing maximum horsepower. Just making life with a three-row SUV easier. Why Explorer Active makes sense If your typical week consists of: School drop-offs Work Grocery runs Sports practice Family errands Weekend trips Occasional third-row passengers you may not need to move much farther up the lineup. That's important because trim shopping can easily become: "For just a little more, I can get..." Then you repeat that sentence four times and suddenly you're looking at a completely different SUV. Instead, ask: What features will I actually use? If Active already checks the boxes, that's a very good reason to stop there. Who should buy Explorer Active? We'd put it high on the list for: Families Daily commuters Buyers prioritizing value and comfort Shoppers who don't need performance styling Buyers who want available 4WD Anyone looking for a well-rounded Explorer Our take Active is probably the Explorer trim most shoppers should use as their baseline. Drive it first. Then decide whether something on ST-Line, Tremor, ST or Platinum gives you enough additional value to move up. See Available Ford Explorer SUVs 2026 Ford Explorer ST-Line: Sporty Without Going Full ST This is one of the easiest Explorer trims to misunderstand. The ST-Line is not an Explorer ST with a smaller badge. It gives you much of the sporty appearance associated with the ST while retaining the 2.3L EcoBoost powertrain. That's exactly why it exists. Some shoppers love the appearance of the ST but don't necessarily need — or want to pay for — the 3.0L EcoBoost V6. That's the ST-Line shopper. What makes the ST-Line different? Visually, ST-Line takes the Explorer in a much sportier direction. For 2026, Ford equips it with 20-inch Ebony-painted machined aluminum wheels as standard equipment. The overall theme is more aggressive than Active without requiring you to jump all the way to the performance-focused ST. Who should buy Explorer ST-Line? Consider ST-Line if: Exterior styling matters to you. You like blacked-out/sport-inspired details. You want a more aggressive-looking Explorer. The 2.3L EcoBoost already provides the performance you need. You want more technology and available equipment. You like the ST aesthetic but don't need the ST engine. This is an important distinction. ST-Line = sporty appearance ST = sporty appearance + serious performance If you're choosing primarily with your eyes, ST-Line can make a lot of sense. If you're choosing with your right foot? You probably want to drive the ST. 2026 Ford Explorer Tremor: The Adventure Explorer This is the biggest addition to the 2026 Explorer lineup. Explorer Tremor is new for 2026. And unlike ST-Line, which primarily changes the Explorer's personality through appearance and equipment, Tremor is about capability. The Tremor comes standard with Intelligent 4WD rather than offering rear-wheel drive as an alternative. Ford also gives it 18-inch Ebony Black-painted wheels with all-terrain tires, helping distinguish it from the more street-focused Explorer trims. What engine does the Explorer Tremor have? Here's where Tremor gets particularly interesting. The standard engine is the 2.3L EcoBoost. But the 3.0L EcoBoost V6 is available. That means you can configure Tremor in two very different ways. 2.3L Tremor Makes sense if you want the Tremor's capability and styling without needing the more powerful V6. 3.0L Tremor This is for someone who wants the more adventure-focused Explorer and considerably more power. Ford pairs the 3.0L Tremor with its Tremor Ultimate Package, which brings additional premium equipment into the mix. Who should buy Explorer Tremor? We'd consider Tremor if: You regularly drive on gravel, dirt or rougher roads. Camping is part of your lifestyle. You spend weekends in the mountains. Standard 4WD matters. You want all-terrain tires from the factory. You want an Explorer that looks and feels more adventure-focused. You like the idea of pairing Tremor capability with the available 3.0L EcoBoost. For drivers in the Piedmont Triad who regularly head toward Boone, Blowing Rock, the Blue Ridge or campsites around North Carolina, Tremor gives Explorer shoppers an option they didn't previously have. But be realistic. If your Explorer will spend 99.9% of its life on pavement between High Point and Greensboro, you don't need Tremor. You may still want it. That's different. Explorer Tremor vs. ST-Line These two trims may appeal to shoppers who want something more visually interesting than Active. But they have very different personalities. Choose ST-Line if: You want a sporty-looking Explorer primarily for pavement. Choose Tremor if: You want an adventure-oriented Explorer with standard 4WD and all-terrain equipment. Think: ST-Line = street Tremor = trail That's oversimplified, but it's a useful starting point. 2026 Ford Explorer ST: The Performance Choice Now we get to the Explorer that actually backs up its sporty appearance with a different engine. The 2026 Explorer ST uses a 3.0L EcoBoost V6 producing up to 385 horsepower and 415 lb.-ft. of torque. That's a substantial jump from the 2.3L EcoBoost used by Active and ST-Line. Ford also gives the ST a sport-tuned suspension, 21-inch Magnetite-painted aluminum wheels and other performance-oriented equipment. This isn't simply an appearance package. The ST drives differently. Who should buy Explorer ST? Consider the ST if: You genuinely enjoy driving. Acceleration matters to you. You want the 3.0L EcoBoost V6. You want a sport-tuned suspension. You want three rows without giving up performance. You'd actually appreciate the difference every time you drive it. And that last point matters. If you're never going to care how quickly your family SUV accelerates, you probably don't need the ST. If you get into an ST, accelerate onto the highway and immediately grin? Different story. This is one trim you absolutely should test drive. The reason to pay for an ST isn't simply a list of features. It's how the SUV feels. Schedule a Ford Explorer Test Drive Explorer ST-Line vs. Explorer ST: What's the Difference? This may be the most important trim comparison in the entire lineup. The names are similar. The vehicles aren't. Explorer ST-Line 2.3L EcoBoost Sport-inspired appearance 20-inch standard wheels Designed for shoppers who want the ST look without the ST powertrain Explorer ST 3.0L EcoBoost V6 Up to 385 horsepower Up to 415 lb.-ft. of torque Sport-tuned suspension 21-inch standard wheels Designed for shoppers who actually want increased performance Which should you buy? If you love the look: ST-Line. If you love the performance: ST. If you're unsure whether the ST is worth the additional money, drive both back-to-back. You'll know pretty quickly whether the performance difference matters to you. 2026 Ford Explorer Platinum: The Luxury Choice Platinum takes the Explorer in another direction entirely. Instead of asking: "How can we make Explorer sportier?" Platinum asks: "How can we make Explorer more comfortable and premium?" For 2026, Platinum uses the 2.3L EcoBoost engine. That's worth pointing out because shoppers familiar with previous Explorer model years may remember the availability of the 3.0L EcoBoost on Platinum. For 2026, Ford deleted the 3.0L engine option from Platinum. If you want the V6, you're now looking primarily toward ST or an appropriately equipped Tremor. If you want premium comfort, Platinum remains the luxury-focused Explorer. What makes Platinum different? Ford equips Platinum with upscale design and comfort features, including standard 20-inch Luster Nickel-painted aluminum wheels, with 21-inch wheels available. BlueCruise equipment is also part of the Platinum story, with Ford offering hands-free highway-driving capability under applicable activation plans. The emphasis is less: "Look how aggressive my SUV is." and more: "This is a very comfortable place to spend two hours." Who should buy Explorer Platinum? Consider Platinum if: Interior comfort is a major priority. You want a more upscale Explorer. Premium appointments matter more than performance. You spend significant time commuting or traveling. You're interested in available BlueCruise. You don't need the ST's V6. Platinum vs. ST This is almost entirely about personality. ST: performance. Platinum: luxury. Neither is inherently better. They're built for different buyers. Explorer Active vs. ST-Line: Is ST-Line Worth It? For a lot of shoppers, this is where the decision will happen. Both use the 2.3L EcoBoost. Both can perform the basic family-SUV job extremely well. So why spend more for ST-Line? Mostly because you want what ST-Line adds. If you prefer its appearance and equipment, that's legitimate value. If you're indifferent to styling? Active may give you everything you actually need. This is where we'd encourage shoppers not to get caught in trim creep. If the ST-Line makes you turn around and look at your Explorer after parking it, that matters. If Active looks perfectly good to you? Keep the money. Explorer Active vs. Platinum: How Much Luxury Do You Need? These trims represent two very different approaches to essentially the same family mission. Active says: Give me the features I need. Platinum says: I'm spending a lot of time in this SUV. Make it nice. Both use the 2.3L EcoBoost for 2026. So moving from Active to Platinum isn't primarily about needing more engine. It's about how much you value comfort, appearance, convenience and premium equipment. For someone driving 8,000 miles per year mostly around town, Active may make perfect sense. For someone driving 25,000 miles per year and spending hours every week behind the wheel? Those comfort upgrades may feel much more valuable. Explorer ST vs. Tremor: Performance or Adventure? This may be the most fun comparison in the lineup. Both can be equipped with the 3.0L EcoBoost V6, but they're designed around different priorities. Explorer ST Built around on-road performance. Sport-tuned suspension. 21-inch wheels. Available RWD or 4WD. Explorer Tremor Built around greater off-pavement capability. Standard Intelligent 4WD. 18-inch wheels. All-terrain tires. Available 3.0L EcoBoost. Which one should you buy? Ask where you'll actually drive. If your idea of fun is a curvy paved road: ST. If your idea of fun is the dirt road at the end of it: Tremor. Which 2026 Explorer Trim Is Best for Families? For most families, we'd start with: Explorer Active. Why? Because it gives you the core Explorer experience without requiring you to pay for a specific personality you may not need. Then ask what Active is missing. Need sportier styling? Move to ST-Line. Spend a lot of time camping or on rougher roads? Look at Tremor. Want considerably more performance? Drive the ST. Want more premium comfort? Look at Platinum. That's a much better way to trim-shop than automatically asking: "What's the highest trim?" Which Explorer Trim Is Best for a Daily Commute? We'd compare: Active, ST-Line and Platinum. Active gives you the practical value play. ST-Line adds a sportier look. Platinum emphasizes comfort. If your commute regularly takes you between High Point, Greensboro, Winston-Salem or elsewhere around the Triad, we'd pay particular attention to the features you'll interact with every single day. Seat comfort. Driver-assistance technology. Audio. Interior materials. Wheel/tire configuration. Those things may matter more over 15,000 miles than an off-road feature you'll use twice. Which Explorer Trim Is Best for Road Trips? This one isn't necessarily about trim. All Explorer models give you the basic three-row SUV format. Instead, we'd look at what makes your road trips better. Active Great if you simply need a comfortable family vehicle. ST-Line Good if you want additional style and technology. Platinum Our first look if long-distance comfort is the priority. ST For the parent who wants the road trip to be fun after everyone else falls asleep. Tremor For the family whose road trip destination isn't always at the end of a paved road. Which Explorer Trim Is Best for Snow and Bad Weather? Don't choose solely from the trim badge. Look at the drivetrain and tires. Intelligent 4WD is available on several Explorer trims. Tremor includes 4WD as standard equipment and comes with all-terrain tires, making it particularly interesting for shoppers who prioritize traction and more rugged use. But an Active, ST-Line, ST or Platinum equipped with 4WD may make much more sense for someone who primarily wants additional confidence during poor weather without Tremor's adventure-focused equipment. Which Explorer Has the Most Horsepower? For conventional 2026 Explorer trims, the Explorer ST is the straightforward performance choice. Its 3.0L EcoBoost V6 produces up to: 385 horsepower and 415 lb.-ft. of torque. The 3.0L EcoBoost is also available on Tremor, giving shoppers another route to V6 Explorer power. If horsepower is a major reason you're choosing your trim, don't assume Platinum is the answer simply because it's positioned as a premium model. For 2026: Luxury = Platinum Performance = ST That's an important distinction. Which Explorer Trim Is the Best Value? If we're talking about value rather than lowest price, we'd start with Active. Why? Because it provides the features many families actually want without forcing you into styling, performance, off-road or luxury upgrades you may not use. But value is personal. For someone who desperately wants an ST, buying an Active and wishing every day that they'd bought the V6 isn't great value. For someone who spends 25,000 miles a year commuting, Platinum's comfort features may provide value every single day. For an outdoors-focused family, Tremor's standard 4WD and capability may be worth far more than premium interior trim. The best value is: the least expensive Explorer that gives you the things you'll genuinely miss if you don't have them. What Features Should You Actually Pay For? This is the question we'd ask before choosing any trim. Make three lists. Must Have Features you genuinely won't buy the vehicle without. Examples: 4WD Particular seating configuration Heated seats BlueCruise capability Power liftgate Specific engine Nice to Have Features you'd enjoy but could live without. Don't Care Features that sound impressive but won't change your ownership experience. Then shop the trim that checks your Must Have list without paying unnecessarily for everything on someone else's list. That's how you avoid spending thousands of dollars moving up trims for one feature you wanted. Don't Forget Packages and Options Here's another reason trim comparisons aren't always straightforward: Two Explorers with the same trim badge may not have identical equipment. Ford offers packages and standalone options that can substantially change an Explorer's features. For example, 2026 brings an available panoramic fixed glass roof with power shade across the Explorer lineup, while trims such as Tremor have their own convenience and Ultimate packages. BlueCruise availability also varies by trim, equipment and activation choice. So once you've decided: "I think I want an ST-Line" don't stop there. Compare the actual window stickers. You may find one ST-Line has exactly what you want while another doesn't. The VIN matters more than the badge when you're comparing specific vehicles. Browse Available 2026 Ford Explorers Do All 2026 Ford Explorers Have Three Rows? Yes, Explorer remains a three-row SUV. Depending on seating configuration, the 2026 Explorer can accommodate up to seven passengers. One noteworthy 2026 change is that Ford now makes a second-row bench seat available on the ST, giving performance-focused shoppers another seating option. That's useful for families who previously might have liked the ST but needed a different seating arrangement. Can a 2026 Ford Explorer Tow? Yes. Ford rates the 2026 Explorer for up to 5,000 pounds of maximum towing capacity when properly equipped. The Class III Trailer Tow Package is standard across the Explorer lineup. But remember: The maximum number doesn't mean every towing situation is automatically appropriate. Trailer weight, passengers, cargo and the specific vehicle configuration still matter. If you're buying an Explorer to tow a boat or camper, bring the trailer information with you when you shop. We'll help you look at the actual Explorer you're considering rather than relying solely on a maximum number from a brochure. Explorer or Expedition? Sometimes trim shopping reveals a bigger question. Suppose you're looking at Explorer Platinum because you need more family space. Or you're loading an Explorer with seven passengers and realizing you won't have as much cargo room behind the third row as you'd like. You may not need a different Explorer trim. You may need an Expedition. We've already built a full comparison for exactly that question. RELATED READING 2026 Ford Explorer vs. Expedition: Which 3-Row SUV Fits Your Family? That guide compares the two SUVs based on passenger space, cargo, towing and everyday family use. What If You Need Something Smaller Than an Explorer? The opposite can happen too. Maybe you're shopping Explorer because you want an SUV, but: You rarely carry more than four people. You don't need three rows. You primarily commute. A smaller footprint would be easier every day. In that case, don't pay for space you don't need. A smaller Ford SUV may make more sense. The goal isn't to sell yourself the biggest SUV your budget allows. It's to find the vehicle you'll actually enjoy living with. Trading Your Current Vehicle for an Explorer? Your trade can also affect which Explorer trim comfortably fits your budget. You may assume ST or Platinum is out of reach until you discover you have substantial positive equity. Or you may decide Active is the smarter choice once you know the full transaction. Start by finding out what your current vehicle is worth. Find Out What Your Vehicle Is Worth Related Reading What Is My Car Worth in High Point, NC? How Trade-In Appraisals Actually Work If you still have a loan: Can You Trade In a Car You Still Owe Money On? How Much Should You Put Down on an Explorer? Once you've chosen a trim, the next question may be how to structure the purchase. There's no universal percentage that every Explorer buyer should put down. Trade equity, APR, loan term, cash reserves and your desired payment all matter. We just built a full guide to help with that decision. RELATED READING How Much Should You Put Down on a Car? That article walks through how different down payments affect the amount financed, payment, interest and equity. Should You Test Drive Different Explorer Trims? Yes — especially if you're deciding between trims with different personalities. Reading a feature list can tell you that ST has a sport-tuned suspension and a 3.0L EcoBoost. It can't tell you whether you care about the difference. Likewise, you may discover: Active already gives you everything you need. ST-Line's appearance is worth the upgrade to you. Tremor's ride and equipment fit your lifestyle. ST's additional performance completely changes your decision. Platinum's comfort makes it the obvious choice. If possible, drive your top two trims back-to-back. That's particularly useful for: Active vs. ST-Line ST-Line vs. ST ST vs. Tremor ST vs. Platinum Schedule a Ford Explorer Test Drive Which 2026 Ford Explorer Should You Buy? Here's our final breakdown. Buy Explorer Active 100A if: You want the essential Explorer experience at the lowest point of entry and don't mind giving up some convenience equipment. Buy Explorer Active if: You want a comfortable, well-rounded family Explorer without paying for a specialized personality. This is where we'd start most shoppers. Buy Explorer ST-Line if: You want the sporty Explorer appearance but don't need the ST's 3.0L V6. Buy Explorer Tremor if: Your family genuinely spends time away from pavement, you want standard 4WD and all-terrain equipment, or you simply love the adventure-oriented Explorer. Buy Explorer ST if: You want your three-row family SUV to be legitimately quick and fun to drive. Buy Explorer Platinum if: You care more about premium comfort and an upscale driving experience than maximum performance. Compare 2026 Ford Explorer Trims at Crescent Ford in High Point, NC Choosing an Explorer trim doesn't need to be complicated. Start with Active. Then ask yourself what you want that Active doesn't give you. Want the sporty look? ST-Line. Want to head farther off pavement? Tremor. Want the V6 and on-road performance? ST. Want the premium experience? Platinum. Want to keep the price as low as possible while still getting an Explorer? Active 100A. For Explorer shoppers around High Point, Greensboro, Winston-Salem, Kernersville, Thomasville, Lexington, Trinity and the surrounding Piedmont Triad, comparing the actual vehicles in person is the easiest way to determine whether moving up a trim is worth it. At Crescent Ford, you can compare available Explorer trims, check the equipment on individual vehicles and test drive your top choices. Because the best Explorer isn't necessarily the one with the longest feature list. It's the one that gives your family the features you'll actually use. Shop New Ford Explorer SUVs at Crescent Ford Schedule a Test Drive Value Your Trade Explore Financing Options Frequently Asked Questions About 2026 Ford Explorer Trim Levels What are the 2026 Ford Explorer trim levels? The 2026 Explorer lineup includes Active 100A, Active, ST-Line, Tremor, ST and Platinum. Active 100A and Tremor are new additions for the 2026 model year. What is the difference between Explorer Active 100A and Active? Active 100A is a simplified entry configuration designed to provide the essential Explorer experience at a lower point of entry. The regular Active adds convenience equipment, including a power liftgate and additional comfort features. Compare individual window stickers because equipment can vary. What is the difference between Explorer ST-Line and ST? The ST-Line uses the 2.3L EcoBoost engine and emphasizes sporty styling. The ST uses a 3.0L EcoBoost V6 producing up to 385 horsepower and 415 lb.-ft. of torque and adds performance-oriented equipment including a sport-tuned suspension. Is the 2026 Explorer Tremor new? Yes. Tremor joins the Explorer lineup for 2026 and comes standard with Intelligent 4WD, 18-inch wheels and all-terrain tires. A 3.0L EcoBoost V6 is also available. Does the Explorer Tremor have a V6? It can. The 2.3L EcoBoost is standard on the 2026 Explorer Tremor, while the 3.0L EcoBoost V6 is available. Which 2026 Explorer has a V6? The Explorer ST comes standard with the 3.0L EcoBoost V6. The 3.0L EcoBoost is also available on Tremor. Platinum no longer offers the 3.0L EcoBoost for the 2026 model year. Which Explorer trim is best for a family? For many families, Active is a strong starting point because it balances everyday comfort, three-row practicality and available 4WD without requiring shoppers to pay for specialized performance, off-road or luxury equipment. Which Explorer trim is the most luxurious? Platinum is the luxury-focused trim in the 2026 Explorer lineup, emphasizing premium comfort and upscale features rather than the performance focus of ST. Which Explorer trim is the fastest? The ST is the performance-focused Explorer, using a 3.0L EcoBoost V6 producing up to 385 horsepower and 415 lb.-ft. of torque along with a sport-tuned suspension. Is Explorer ST-Line the same as Explorer ST? No. Although they share sporty styling themes, ST-Line uses the 2.3L EcoBoost engine while ST gets the more powerful 3.0L EcoBoost V6 and performance-oriented suspension. Is Explorer Tremor or ST better? It depends on how you drive. ST is designed around on-road performance, while Tremor emphasizes off-pavement capability with standard Intelligent 4WD and all-terrain tires. Tremor can also be equipped with the 3.0L EcoBoost V6. Does the 2026 Explorer Platinum have the 3.0L V6? No. Ford's 2026 Explorer order guide shows the 3.0L EcoBoost option deleted from the Platinum trim for the 2026 model year. Platinum uses the 2.3L EcoBoost engine. Does the 2026 Ford Explorer have 4WD? Intelligent 4WD is available on Active 100A, Active, ST-Line, ST and Platinum. Tremor comes with Intelligent 4WD as standard equipment. How many people does the 2026 Ford Explorer seat? The 2026 Explorer offers three-row seating for up to seven people depending on configuration. Ford also added second-row bench-seat availability to the ST for 2026. How much can a 2026 Ford Explorer tow? The 2026 Ford Explorer can tow up to 5,000 pounds when properly equipped. Actual capability depends on the vehicle configuration, passengers, cargo and trailer. Should I test drive different Explorer trims before buying? Yes. A back-to-back test drive is particularly useful when comparing trims such as Active vs. ST-Line or ST-Line vs. ST because differences in styling, equipment and performance may matter more in person than they do on a specification sheet. Schedule a Ford Explorer Test Drive to compare the trims you're considering.